
Which of the following statements is true regarding the management-by-objectives method?
A. Management by objectives is most helpful in organizations that have rapid changes
B. Management by objectives is most helpful in mechanistic organizations with rigidly defined tasks
C. Management by objectives helps organizations to keep employees motivated.
D. Management by objectives helps organizations to distinguish clearly strategic goals from operational goals
Explanation:
Management by objectives (MBO) is a performance management approach in which managers and employees jointly set specific, measurable goals, monitor progress toward them, and evaluate performance based on the achievement of those goals. A key benefit of MBO is that it increases employee motivation and commitment because employees participate in setting their own objectives, understand what is expected of them, and receive feedback on their progress. This participative goal-setting process aligns individual objectives with organizational objectives and gives employees a clear sense of purpose and ownership, which drives motivation and engagement.
Why the other options are incorrect:
A. Management by objectives is most helpful in organizations that have rapid changes – MBO relies on setting stable, measurable objectives over a defined period. In organizations experiencing rapid changes, objectives may become obsolete quickly, making MBO less effective. More flexible or adaptive approaches are typically better suited to highly dynamic environments.
B. Management by objectives is most helpful in mechanistic organizations with rigidly defined tasks – MBO emphasizes participation, communication, and individual goal setting, which aligns better with organic, flexible structures. In mechanistic organizations with rigidly defined tasks, there is less room for the participative goal-setting that makes MBO effective, so this statement is inaccurate.
D. Management by objectives helps organizations to distinguish clearly strategic goals from operational goals – While MBO does cascade objectives from top to bottom and can link individual goals to organizational goals, its primary purpose is not to distinguish strategic from operational goals. MBO focuses on setting and achieving performance objectives at all levels; the distinction between strategic and operational goals is handled through other planning frameworks.
📚 Reference:
IIA-CIA-Part3 content area on Business Acumen / Organizational Behavior – Covers performance management approaches, including management by objectives and employee motivation.
Following an evaluation of an organization's IT controls, an internal auditor suggested improving the process where results are compared against the input. Which of the following IT controls would the Internal auditor recommend?
A. Output controls
B. Input controls
C. Processing controls
D. Integrity controls
Explanation:
Output controls are designed to ensure the accuracy, completeness, and validity of the results produced by an IT system. They involve comparing the processed results (output) against the original input or expected results to verify that the system processed the data correctly. When an internal auditor suggests improving the process where results are compared against the input, this directly describes an output control activity. Examples include reconciliation of output totals to input totals, review of output reports for reasonableness, and distribution controls to ensure outputs reach authorized users only.
Why the other options are incorrect:
B. Input controls – Input controls focus on ensuring that data entered into the system is accurate, complete, authorized, and valid at the point of entry. They address the quality of data going into the system (e.g., edit checks, validation routines, batch controls), not the comparison of results against the input after processing has occurred.
C. Processing controls – Processing controls are designed to ensure that data is processed accurately and completely during the processing stage itself (e.g., run-to-run controls, control totals, error reports). While they relate to the processing of data, they do not specifically describe the comparison of final results against the original input, which is the hallmark of output controls.
D. Integrity controls – Integrity controls are broad safeguards that ensure data remains accurate, consistent, and protected from unauthorized modification throughout its lifecycle. While related to data reliability, this is a general category rather than the specific control that compares results (output) against input, so it is not the best answer here.
📚 Reference:
* IIA-CIA-Part3 content area on Information Technology – Covers IT general and application controls, including input, processing, and output controls.
An internal auditor observed that the organization's disaster recovery solution will make use of a cold site in a town several miles away. Which of the following is likely to be a characteristic of this disaster recover/ solution?
A. Data is synchronized in real time
B. Recovery time is expected to be less than one week
C. Servers are not available and need to be procured
D. Recovery resources end data restore processes have not been defined.
Explanation:
A cold site is a disaster recovery facility that provides basic infrastructure, such as physical space, power, HVAC, and network connectivity, but does not include pre-installed hardware, software, or configured systems. Because servers and other equipment are not available at a cold site, the organization must procure, install, and configure them after a disaster occurs. This makes the cold site the least expensive recovery option but also the one with the longest recovery time, since rebuilding the environment from scratch takes considerable effort. The characteristic that servers are not available and need to be procured accurately describes a cold site.
Why the other options are incorrect:
A. Data is synchronized in real time – Real-time data synchronization is a characteristic of a hot site, where systems and data are continuously replicated and kept ready for immediate failover. A cold site has no pre-installed systems or synchronized data, so this statement does not apply.
B. Recovery time is expected to be less than one week – A cold site typically requires days to weeks to become operational because hardware must be procured, installed, and configured, and data must be restored. A recovery time of less than one week is more consistent with a warm or hot site, not a cold site.
D. Recovery resources and data restore processes have not been defined – Even with a cold site, the organization should still have defined recovery resources, procedures, and data restore processes as part of its disaster recovery plan. The distinguishing feature of a cold site is the absence of pre-installed equipment, not the absence of planning or defined processes.
Reference:
IIA-CIA-Part3 content area on Business Continuity Management (BCM) and Disaster Recovery Planning – Covers alternate site strategies, including hot, warm, and cold sites.
Which of the following is required in effective IT change management?
A. The sole responsibility for change management is assigned to an experienced and competent IT team
B. Change management follows a consistent process and is done in a controlled environment.
C. Internal audit participates in the implementation of change management throughout the organisation.
D. All changes to systems must be approved by the highest level of authority within an organization.
Explanation:
Effective IT change management requires that all changes to IT systems, infrastructure, and applications follow a consistent, standardized, and repeatable process. This typically includes requesting, reviewing, approving, testing, implementing, and documenting changes in a controlled environment (such as a test or staging environment) before deployment to production. A consistent process ensures that changes are authorized, assessed for risk and impact, tested adequately, and implemented with minimal disruption to operations. Performing changes in a controlled environment reduces the risk of unintended consequences, errors, and system failures.
Why the other options are incorrect:
A. The sole responsibility for change management is assigned to an experienced and competent IT team – Effective change management requires involvement from multiple parties, including IT, business users, and management, not solely an IT team. Assigning sole responsibility to one team creates a lack of segregation of duties, insufficient oversight, and potential blind spots in risk assessment and approval.
C. Internal audit participates in the implementation of change management throughout the organisation – Internal audit's role is to provide independent, objective assurance and consulting services. Participating in the implementation of change management would impair internal audit's independence and objectivity. Internal auditors may review and evaluate change management processes, but they should not implement or manage them.
D. All changes to systems must be approved by the highest level of authority within an organization – Requiring every change, including routine or minor changes, to be approved by the highest level of authority is impractical and inefficient. Effective change management uses a tiered approval structure based on the significance, risk, and impact of the change, with routine changes handled at appropriate lower levels of authority.
Reference:
IIA-CIA-Part3 content area on Information Technology – Covers IT change management and control processes.
Based on lest results, an IT auditor concluded that the organization would suffer unacceptable loss of data if there was a disaster at its data center. Which of the following test results would likely lead the auditor to this conclusion?
A. Requested backup tapes were not returned from the offsite vendor In a timely manner.
B. Returned backup tapes from the offsite vendor contained empty spaces.
C. Critical systems have boon backed up more frequently than required.
D. Critical system backup tapes are taken off site less frequently than required
Explanation:
The maximum acceptable amount of data loss following a disaster is governed by the organization's Recovery Point Objective (RPO).
Impact of Infrequent Off-Site Backups: If critical system backups are taken off-site less frequently than required (e.g., weekly instead of daily), any disaster affecting the main data center between off-site transfers will destroy all recent data generated since the last off-site shipment. Because the local backups at the data center are lost in the disaster, the organization can only restore data up to the date of the last off-site tape, directly causing an unacceptable loss of data beyond the defined RPO.
Why the Incorrect Options Fail:
A. Requested backup tapes were not returned from the offsite vendor in a timely manner – This is incorrect because delays in retrieving off-site tapes primarily impact the Recovery Time Objective (RTO), increasing the duration of downtime, rather than causing permanent loss of data (RPO).
B. Returned backup tapes from the offsite vendor contained empty spaces – This is incorrect because unused or empty space on magnetic backup tapes is normal behavior and simply indicates that the volume of backed-up data did not fill the tape's maximum storage capacity.
C. Critical systems have been backed up more frequently than required – This is incorrect because backing up systems more frequently than required reduces potential data loss and improves recovery capability rather than causing unacceptable data loss.
Reference:
IIA CIA Exam Syllabus, Part 3, Section IV – Information Technology & Business Continuity – Covers disaster recovery planning, RPO versus RTO metrics, and off-site storage controls.
Which of the following inventory costing methods requires the organization to account for the actual cost paid for the unit being sold?
A. Last-in-first-Out (LIFO}.
B. Average cost.
C. First-in-first-out (FIFO).
D. Specific identification
Explanation:
The specific identification method is an inventory costing method in which the organization tracks the actual cost of each individual unit of inventory and charges that exact cost to cost of goods sold when the unit is sold. This method requires detailed recordkeeping because each item must be uniquely identified (e.g., by serial number, lot number, or tag) so that its actual purchase cost can be matched to its sale. It is typically used for high-value, low-volume, or uniquely identifiable items such as automobiles, jewelry, or custom-made goods. Because it uses the actual cost paid for the specific unit being sold, it is the only method that directly meets the requirement described in the question.
Why the other options are incorrect:
A. Last-in-first-out (LIFO) – LIFO assumes that the most recently purchased units are sold first, so cost of goods sold is based on the cost of the latest purchases, not the actual cost of the specific unit sold. It is a cost flow assumption rather than a method of tracking actual unit costs.
B. Average cost – The average cost method calculates a weighted average cost per unit and assigns that average cost to cost of goods sold and ending inventory. It does not track or account for the actual cost paid for the specific unit being sold; instead, it blends costs across all units.
C. First-in-first-out (FIFO) – FIFO assumes that the oldest units are sold first, so cost of goods sold is based on the cost of the earliest purchases, not the actual cost of the specific unit sold. Like LIFO, it is a cost flow assumption rather than a method based on actual unit identification.
Reference:
* IIA-CIA-Part3 content area on Financial Management / Accounting – Covers inventory costing methods and their impact on financial statements.
An organization produces products X and Y. The materials used for the production of both
products are limited to 500 Kilograms
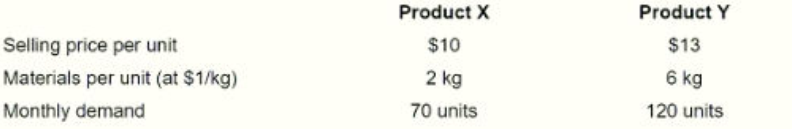
(kg ) per month. All other resources are unlimited and their costs are fixed. Individual
product details are as follows in order to maximize profit, how much of product Y should the
organization produce each month?
$10 $13
2 kg
70 units
6 kg
120 units
A. 50 units
B. 60 units
C. 70 units
D. 1:20 units
Explanation:
When a single resource (materials) is limited and all other resources are unlimited with fixed costs, the organization should maximize profit by producing the product that generates the highest contribution per unit of the scarce resource (materials). First, calculate the contribution per kilogram of material for each product:
Product X: Selling price $10 ÷ 2 kg = $5 per kg
Product Y: Selling price $13 ÷ 6 kg = $2.17 per kg
Since Product X generates a higher contribution per kilogram ($5 vs. $2.17), the organization should first satisfy the full monthly demand for Product X, then use the remaining materials for Product Y.
Materials needed for Product X: 70 units × 2 kg = 140 kg
Materials remaining for Product Y: 500 kg − 140 kg = 360 kg
Units of Product Y that can be produced: 360 kg ÷ 6 kg per unit = 60 units
Therefore, to maximize profit, the organization should produce 70 units of Product X and 60 units of Product Y.
Why the other options are incorrect:
A. 50 units – Producing only 50 units of Product Y would leave 60 kg of material unused (50 × 6 = 300 kg; 360 − 300 = 60 kg remaining). This does not maximize profit because the organization could produce 10 more units of Y with the available material, generating additional contribution.
C. 70 units – Producing 70 units of Product Y would require 420 kg (70 × 6), plus 140 kg for Product X, totaling 560 kg, which exceeds the 500 kg limit. This is not feasible.
D. 120 units – Producing 120 units of Product Y would require 720 kg (120 × 6), far exceeding the 500 kg material limit, and would also leave no material for Product X, which has the higher contribution per kg. This is not feasible and not optimal.
Reference:
* IIA-CIA-Part3 content area on Financial Management / Managerial Accounting – Covers limiting factors, contribution margin analysis, and profit maximization under resource constraints.
Which of the following capital budgeting techniques considers the expected total net cash flows from investment?
A. Cash payback
B. Annual rate of return
C. Incremental analysis
D. Net present value
Explanation:
Net present value (NPV) is a capital budgeting technique that considers the expected total net cash flows from an investment over its entire useful life. It discounts all expected future net cash inflows and outflows back to their present value using a required rate of return (or discount rate) and compares the total present value of inflows against the initial investment. If the NPV is positive, the investment is expected to increase the organization's value and is generally accepted; if negative, it is typically rejected. Because NPV incorporates all expected net cash flows across the project's life and accounts for the time value of money, it is the technique that best reflects the total net cash flows from an investment.
Why the other options are incorrect:
A. Cash payback – The cash payback technique measures how long it takes for an investment to recover its initial cost from net cash inflows. It focuses only on the time required to break even and ignores cash flows that occur after the payback period, so it does not consider the expected total net cash flows from the investment.
B. Annual rate of return – The annual rate of return (also called accounting rate of return) uses accounting net income rather than cash flows and compares average annual income to the average investment. It does not consider total net cash flows and ignores the time value of money.
C. Incremental analysis – Incremental analysis is a general decision-making approach that compares the relevant differences in revenues, costs, and cash flows between alternatives. While it may be used in capital budgeting, it is not a specific capital budgeting technique that systematically evaluates total net cash flows over a project's life in the way NPV does.
Reference:
IIA-CIA-Part3 content area on Financial Management – Covers capital budgeting techniques, including net present value, internal rate of return, payback, and accounting rate of return.
Which of the following networks is suitable for an organization that has operations In multiple cities and countries?
A. Wide area network.
B. Local area network
C. Metropolitan area network
D. Storage area network
Explanation:
A wide area network (WAN) is a network that spans a large geographic area, such as multiple cities, countries, or even continents. It is designed to connect multiple local area networks (LANs) and other networks over long distances, enabling organizations with operations in different locations to communicate, share data, and access centralized resources. WANs typically use leased telecommunication lines, satellites, or internet connections to link geographically dispersed sites, making them the appropriate choice for an organization with operations in multiple cities and countries.
Why the other options are incorrect:
B. Local area network – A local area network (LAN) covers a small geographic area, such as a single building, office, or campus. It is not designed to connect locations across multiple cities or countries, so it is unsuitable for a geographically dispersed organization.
C. Metropolitan area network – A metropolitan area network (MAN) spans a city or a metropolitan region, typically covering an area larger than a LAN but smaller than a WAN. While it can connect multiple locations within a single city, it does not support operations across multiple cities and countries.
D. Storage area network – A storage area network (SAN) is a specialized, high-speed network that provides block-level access to consolidated storage devices. It is used for data storage and retrieval within a data center or among closely located servers, not for connecting geographically dispersed organizational operations.
Reference:
* IIA-CIA-Part3 content area on Information Technology – Covers network types and their appropriate use based on geographic scope.
The internal audit activity has identified accounting errors that resulted in the organization overstating its net income for the fiscal year. Which of the following is the most likely cause of this overstatement?
A. Beginning inventory was overstated for the year.
B. Cost of goods sold was understated for the year.
C. Ending inventory was understated for the year.
D. Cost of goods sold was overstated for the year.
Explanation:
Net income is calculated as revenues minus expenses. Cost of goods sold (COGS) is a major expense on the income statement. If COGS is understated, total expenses are lower than they should be, which causes net income to be overstated. This is one of the most common causes of income overstatement identified in audits. COGS can be understated due to errors such as misclassification of costs, failure to record purchases, or errors in inventory valuation that flow into the COGS calculation.
Why the other options are incorrect:
A. Beginning inventory was overstated for the year – Beginning inventory is added to purchases to determine goods available for sale, and then ending inventory is subtracted to arrive at COGS. If beginning inventory is overstated, COGS would also be overstated, which would cause net income to be understated, not overstated.
C. Ending inventory was understated for the year – Ending inventory is subtracted from goods available for sale to determine COGS. If ending inventory is understated, COGS would be overstated because less is subtracted, which would cause net income to be understated, not overstated. Ending inventory being understated is associated with income understatement.
D. Cost of goods sold was overstated for the year – If COGS is overstated, expenses are higher than they should be, which causes net income to be understated, not overstated. This is the opposite of the situation described in the question.
Reference:
IIA-CIA-Part3 content area on Financial Management / Accounting – Covers the relationship between inventory, cost of goods sold, and net income.
An organization contracted a third-party service provider to plan, design, and build a new facility. Senior management would like to transfer all of the risk to the builder. Which type of procurement contract would the organization use?
A. Cost-plus contract.
B. Turnkey contract.
C. Service contract.
D. Solutions contract.
Explanation:
A turnkey contract is a procurement arrangement in which the organization contracts a third-party provider to plan, design, build, and deliver a fully completed and operational facility or system. Under a turnkey contract, the builder is responsible for the entire project from conception through completion, and the organization simply "turns the key" to take possession of the finished product. Because the builder assumes responsibility for design, construction, performance, and delivery, a turnkey contract transfers the greatest amount of risk to the builder, including risks related to design defects, cost overruns, delays, and performance failures. This makes it the most appropriate contract type when senior management wants to transfer all of the risk to the builder.
Why the other options are incorrect:
A. Cost-plus contract – Under a cost-plus contract, the organization reimburses the contractor for allowable costs plus an agreed-upon profit or fee. This arrangement places most of the cost risk on the organization rather than the builder, because the organization bears the burden of cost overruns. It does not transfer all risk to the builder.
C. Service contract – A service contract is a general agreement for the performance of specific services, such as maintenance, consulting, or support. It does not encompass the full scope of planning, designing, and building a facility, and it does not transfer the comprehensive project risk that a turnkey contract does.
D. Solutions contract – A solutions contract is a broad term sometimes used to describe arrangements where a provider delivers a packaged solution to meet an organization's needs. It is not a standard procurement contract type specifically associated with transferring all design, construction, and performance risk to a builder for a facility project.
Reference:
IIA-CIA-Part3 content area on Business Acumen / Procurement and Contract Management – Covers types of procurement contracts and risk transfer.
According to IIA guidance, which of the following links computers and enables them to - communicate with each other?
A. Application program code
B. Database system
C. Operating system
D. Networks
Explanation:
According to IIA guidance on IT, networks are the components that link computers together and enable them to communicate with each other. A network consists of hardware, software, and transmission media (such as cables, switches, routers, and wireless connections) that allow multiple computers and devices to exchange data, share resources, and communicate across distances. Without a network, computers would operate in isolation and could not share information or resources. This makes networks the correct answer to the question of what links computers and enables communication between them.
Why the other options are incorrect:
A. Application program code – Application program code consists of the instructions and logic that make up software applications, enabling them to perform specific tasks for users. While applications may use a network to communicate, application code itself does not link computers or enable them to communicate with each other.
B. Database system – A database system is a structured collection of data and the software used to manage, store, and retrieve that data (e.g., a database management system). It organizes and provides access to data, but it does not link computers together or serve as the communication mechanism between them.
C. Operating system – An operating system is the software that manages a computer's hardware and provides services for applications (e.g., Windows, Linux). While operating systems include networking capabilities, the operating system itself is not what links computers together; it is the network infrastructure that enables communication between computers.
Reference:
IIA-CIA-Part3 content area on Information Technology – Covers IT infrastructure components, including networks, hardware, software, and databases.
| Page 13 out of 58 Pages |
| 456789101112131415161718192021 |
| IIA-CIA-Part3 Practice Test Home |
Real-World Scenario Mastery: Our IIA-CIA-Part3 practice exam don't just test definitions. They present you with the same complex, scenario-based problems you'll encounter on the actual exam.
Strategic Weakness Identification: Each practice session reveals exactly where you stand. Discover which domains need more attention, before Certified Internal Auditor Part 3 - Internal Audit Function exam day arrives.
Confidence Through Familiarity: There's no substitute for knowing what to expect. When you've worked through our comprehensive IIA-CIA-Part3 practice exam questions pool covering all topics, the real exam feels like just another practice session.
Copyright © All Rights Reserved